


 14 September 2026

Market Summary:
-
Global Equity: Global equities ended the week mostly lower, with the S&P 500 declining -0.8% and Nikkei falling -1.55%, amid renewed geopolitical tensions and shifting expectations for global monetary policy. In contrast, KOSPI gained 3.33%, outperforming regional peers.
-
Domestic Equity: The JCI declined 1.43% over the week after briefly reaching a three-month high of 6,678 intra-week. Foreign net selling of IDR 3.4tn for the week.
-
Domestic Bond Market: The 10Y IndoGB yield rose to 7.15%, broadly tracking the upward move.
Key News of The Week:
-
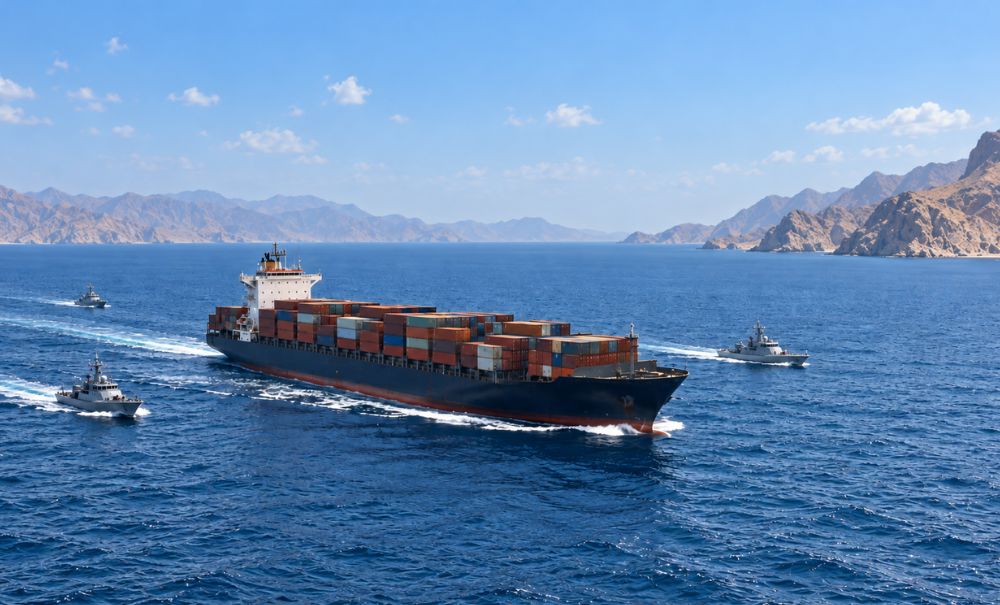
infrastructure, alongside continued hostilities between the US and Iran, heightened concerns over regional energy supplies and shipping routes. Iran-backed Houthi forces seized the Yemeni port city of Mocha and advanced toward the Bab el-Mandeb Strait, raising risks to a key Red Sea shipping corridor. With the Strait of Hormuz also disrupted, simultaneous pressure on the region’s two major energy chokepoints has amplified global oil supply concerns.
-
US CPI accelerated to +0.4% MoM and +3.4% YoY in August, while core CPI rose +0.3% MoM and +2.4% YoY. The hotter-than-expected inflation data reinforced a more hawkish Fed outlook, with markets pricing in an 87.3% probability of a 25bps rate hike at next week’s FOMC meeting, according to CME Group FedWatch. Inflation continued to outpace wage growth, as average hourly earnings rose 3.1% YoY, while real average hourly earnings declined 0.1% MoM and 0.3% YoY.
-
The ECB raised its deposit facility rate by 25bps to 2.5%, citing persistent inflation pressures and rising risks from the Middle East conflict. Eurozone GDP expanded 0.6% QoQ in 2Q26, while UK GDP growth accelerated to 0.4% MoM in July from 0.3% in June.
-
Japanese markets came under pressure as expectations for a BOJ rate hike strengthened. The JPY appreciated sharply early in the week, while JGB yields rose as markets increasingly priced a 25bps hike to 1.25% at the September 17–18 meeting. Japan’s economic momentum remained resilient, with 2Q26 GDP growth revised up to 1.4% annualized and real wages rising 2.4% YoY in July.
Our View
Stronger-than-expected US labor data and elevated inflation have increased expectations for a Fed rate hike at next week’s FOMC, potentially pressuring global equities, bonds, and gold. Middle East tensions remain a key risk given their potential to disrupt energy supplies and global supply chains.
Product Recommendation:
RD MISB, RD MMUSD, RD IDAMAN, RD MIDU, RD MIDSYA, RD MGSED, RD MASED, MICB, MITRA, MITRAS, RD FTSE, ETF LQ45, ETF SRI Kehati, ETF Mandiri Emas Syariah.
Discover a detailed analysis of this week’s market performance in our comprehensive Weekly Market Recap: Read More
| PRODUCT | 3M PERFORMANCE | YTD PERFORMANCE |
|---|---|---|
| JCI | +11.13% | -24.35% |
| LQ45 | +10.71% | -23.25% |
| EQUITY | ||
| MITRA A | +10.98% | -14.79% |
| MICB A | +10.17% | -14.54% |
| ASEAN5 | +8.80% | -17.31% |
| MGSED | -2.52% | +12.33% |
| INDEX | ||
| FTSE ESG A | +8.87% | -16.51% |
| ETF | ||
| XMLF | +11.63% | -19.65% |
| BALANCED | ||
| MISB | -6.14% | -6.64% |
| MIA | -9.60% | -9.33% |
| FIXED INCOME | ||
| MIDU A | -0.33% | -0.59% |
| MIDO2 | -1.85% | -2.21% |
| IDAMAN A | -4.10% | -4.31% |
| MONEY MARKET | ||
| MIPU A | +2.15% | +2.01% |
| MMUSD | +1.82% | +1.71% |
*The data above is as of September, 11th, 2026
For More Information
Contact Mandiri Investasi – (021) 526 3505
Email Mandiri Investasi – [email protected]
Mandiri Investasi – mandiri-investasi.co.id
DISCLAIMER
The information and opinions expressed in this article are for general informational purposes only and are not intended as specific advice or recommendations for any individual, security, or investment product. The content is meant to provide education about the financial industry. Opinions and views presented may change without prior notice. All performance data and investment returns mentioned in this article should not be used as a guarantee or basis for decisions to buy or sell any securities. The data reflects historical performance and does not guarantee future results. Investing in mutual funds carries risks. Investors are advised to carefully read and understand the prospectus before making any investment decisions.
Share It :

Written by


Leave a Reply